FINRA Gift Limit 2026: The New $300 Rule and Client Gift Ideas for Financial Advisors
What FINRA's new $300 gift limit covers, what it doesn't, how to value and record a gift, and client gift ideas at $100, $200 and $300.
As of November 2026, the FINRA gift limit is $300 per person per year. The SEC approved FINRA's amendment to Rule 3220 on February 12, 2026, and it took effect March 30, 2026, raising the cap from $100. It covers business-related gifts from member firms and their associated persons to people outside the firm.
FINRA raised the limit to reflect inflation since it was last set in 1992, which makes this the first holiday season under the new number. This guide covers what counts toward the limit, what is excluded, how to value and record a gift, which other rules can still set a lower ceiling, and gift ideas at three tiers. For client gifting outside regulated industries, see our broader guide to corporate gifts for clients.
This guide is general information, not compliance or legal advice. Your firm's compliance department has the final word on any gift.
What Is the FINRA Gift Limit in 2026?
The FINRA gift limit is $300 per recipient per year, set by Rule 3220 and in effect since March 30, 2026. FINRA announced the change in Regulatory Notice 26-05, published February 27, 2026, after the SEC approved it on February 12. The municipal securities rule, MSRB Rule G-20, has been amended to match.
| Rule | Who it applies to | Limit | Since |
|---|---|---|---|
| FINRA Rule 3220 | FINRA member firms and their associated persons | $300 per person per year (was $100) | March 30, 2026 |
| MSRB Rule G-20 | Dealers that are FINRA members | $300 per person per year | June 1, 2026 |
| MSRB Rule G-20 | Municipal advisors and bank dealers | $100 until the compliance date, then $300 | December 1, 2026 (earlier compliance allowed) |
| IRS business-gift deduction | Any business deducting a gift | $25 deductible per recipient per tax year | Unchanged; not a gift limit |
What Counts Toward the $300 Limit?
Anything of value given to a person outside the firm counts toward the limit when it is given in relation to the business of the recipient's employer. In practice, that means gifts to employees of institutional customers, counterparties and other businesses the firm deals with. Gifts the firm pays for are presumed to be business-related.
- Aggregation: all gifts to one recipient from the firm and all of its associated persons are added together. Each firm's procedures must say whether the year runs on a calendar, fiscal or rolling basis.
- Retail clients: the notice clarifies that Rule 3220 does not apply to gifts to individual retail customers, or to the firm's own associated persons. Firms can still restrict or prohibit those gifts through their own policies.
- Gifts at events: a gift handed over during business entertainment still counts. The cost of the entertainment itself does not.
Ordinary business entertainment, such as a dinner or a game attended with the client, is handled separately. FINRA does not prohibit it as long as it is not so frequent or so extensive as to raise questions of propriety.
Which Gifts Are Excluded From the FINRA Limit?
Five categories fall outside both the $300 limit and the rule's recordkeeping requirement, according to Regulatory Notice 26-05.
- Personal gifts for infrequent life events, such as a wedding or the birth of a child, that are customary, reasonable and personal in nature. The firm cannot bear the cost, directly or indirectly.
- Bereavement gifts that are customary and reasonable.
- De minimis items, such as pens or notepads, and logo items of nominal value. Their value must be substantially below $300; FINRA says amounts above or near $300 are not nominal.
- Commemorative items: customary, reasonable and solely decorative pieces marking a business transaction, even if they cost more than $300.
- Disaster donations made in response to a natural event the President has declared a major disaster.
Adding your firm's logo does not by itself make a gift nominal. A branded jacket or speaker is valued at what it cost, the same as an unbranded one, and counts toward the limit in full. The exclusion is for small, low-value items, not premium gifts that happen to carry a logo.
How Do You Value and Record a Client Gift?
Under the amended rule, gifts are valued at cost, excluding tax and delivery charges. Tickets to sporting or other events are the exception: they are valued at the higher of cost or face value. When one gift goes to several people, the firm records each recipient's name and divides the value among them pro rata.
Firms must have systems reasonably designed to ensure covered gifts are reported, reviewed for compliance and kept in the firm's books and records. The person giving the gift cannot be the one who decides whether it is business-related. A practical checklist for each gift:
- Record the recipient's name, employer and the date the gift was given.
- Record the gift and its cost, before tax and delivery.
- Check the recipient's running total for the year against $300, using your firm's aggregation method.
- Send it through your firm's review before the gift goes out.
- Keep the invoice or receipt with the record.
Which Other Rules Can Set a Lower Limit?
FINRA's $300 is a ceiling under one rule, and other rules or policies can still require less. Law firms reviewing the change, including Morgan Lewis, have stressed that lower limits still apply in several places:
- Your firm's policy: firms may keep a lower internal limit, or restrict gifts to retail clients the rule itself does not cover.
- The recipient's employer: the recipient's company may cap what its people can accept, and that cap applies whatever FINRA allows.
- ERISA plan fiduciaries: under a Department of Labor enforcement policy, gifts to a plan fiduciary from one source are treated as insubstantial only when their aggregate value is less than $250 a year.
- Public officials: state and local governments have their own gift and pay-to-play rules, which vary by jurisdiction and often lack a de minimis exception as broad as FINRA's.
- Municipal advisors and bank dealers: under MSRB Rule G-20 they stay at $100 until December 1, 2026, unless they choose to comply with the new limit early.
Does the $300 Limit Change What You Can Deduct?
No. The IRS still limits the business-gift deduction to $25 per recipient per tax year, so the FINRA limit and the tax deduction are two separate numbers. A $300 gift is allowed under Rule 3220, but only $25 of it is deductible as a business gift.
IRS Publication 463 says incidental costs such as engraving, packaging, insuring and mailing generally do not count toward the $25, and items costing $4 or less with your name permanently imprinted, distributed widely, are not treated as gifts at all. Gifts to your own employees follow different rules; see are employee gifts taxable? This is general information, not tax advice; confirm the treatment with your tax advisor.
What Are Good Client Gifts at $100, $200 and $300?
The best client gifts for financial advisors are useful, recognizably premium and easy to value, because every one has to be logged at cost. Setting three tiers below your firm's limit keeps choices simple for advisors and reviews quick for compliance.
| Tier | Best for | Gift ideas |
|---|---|---|
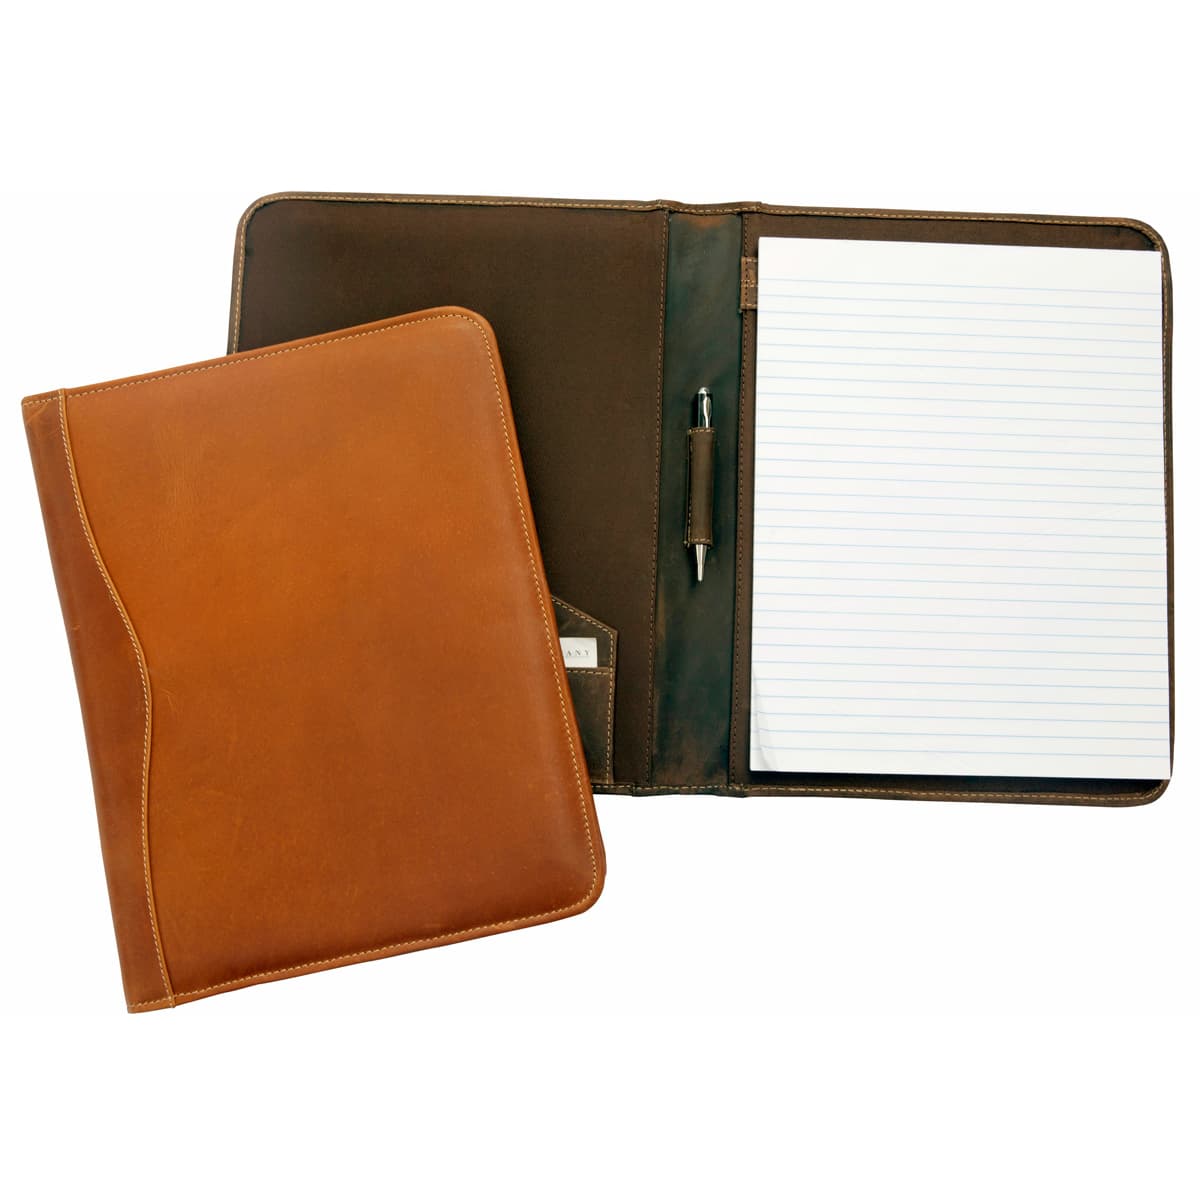
| Around $100 | Broad client lists, institutional contacts, holiday thank-yous | Insulated drinkware from YETI, Stanley or BrüMate; a leather portfolio; a compact JBL speaker |
| Around $200 | Key relationship contacts, year-end thank-yous | A Patagonia or The North Face fleece; an Ember temperature-control mug; a Bose portable speaker; a premium backpack |
| Up to $300 | Your most important relationships, where firm policy allows | Outerwear from The North Face or Patagonia; premium headphones; a cooler from YETI or BrüMate |
Leave headroom. If the same person might also receive a gift from a colleague, or a second gift later in the year, a tier near $300 can push their running total over. For year-end timing and carrier dates, see last-minute corporate holiday gifts, and for what to write on the card, our holiday gift message examples.
How Can a Firm Run Client Gifting Within the Limit?
The simplest way to stay within the limit at scale is to fix one budget per recipient, below your firm's threshold, and let each recipient choose within it. Every gift then carries a known value, and nobody has to guess sizes or collect home addresses.
That is how a corporate gifting pop-up shop works. Idea Tree Engagement builds a fully branded shop with a curated selection from 200+ premium brands; each client opens one link, picks a gift and enters their own address. A dedicated gifting expert curates the selection with you, so your compliance team can approve the tiers before anything goes live. Once we have your brief and your logo, your shop is live within 24 hours, and we handle sourcing, branding, fulfillment and individual shipping, then send one consolidated invoice. Firms in regulated professions already trust us, including the law firms Fish & Richardson, Weil Gotshal & Manges and Bradley.
See how it works, or read why letting recipients choose their gift beats picking one item for everyone. For lead times, tiers and pricing for your list, talk to your gifting expert.
Frequently Asked Questions
What is the FINRA gift limit in 2026?
As of November 2026, FINRA Rule 3220 caps business-related gifts at $300 per recipient per year. The SEC approved the increase from $100 on February 12, 2026, and it took effect March 30, 2026, as announced in FINRA Regulatory Notice 26-05.
Does the FINRA $300 gift limit apply to gifts to retail clients?
No. Regulatory Notice 26-05 clarifies that Rule 3220 does not apply to gifts from a member firm or its associated persons to individual retail customers. Your firm's own policy may still limit or prohibit those gifts, so check with compliance.
Is a gift with our firm's logo excluded from the FINRA limit?
Only if it is a de minimis item of nominal value, such as a pen or notepad. FINRA says the value must be substantially below $300. A premium branded item is valued at its cost and counts toward the limit like any other gift.
How is a gift valued under FINRA Rule 3220?
At cost, excluding tax and delivery charges. Event tickets are valued at the higher of cost or face value, and a gift shared by several recipients is divided among them pro rata.
Can a firm deduct a $300 client gift?
Only $25 of it as a business gift. The IRS limit of $25 per recipient per tax year is unchanged, and it is separate from FINRA's gift limit. This is general information, not tax advice; confirm with your tax advisor.
Do municipal advisors follow the $300 limit?
MSRB Rule G-20 now matches the $300 limit. It became operative June 1, 2026 for dealers that are FINRA members; municipal advisors and bank dealers must comply by December 1, 2026 and may adopt it earlier.
Sources
- Regulatory Notice 26-05: Amendments to FINRA Rule 3220 (Gifts) — FINRA
- MSRB Notice 2026-04: MSRB Amends Rule G-20 to Increase Gift Limit, Consistent with Recent FINRA Amendments — MSRB
- Publication 463, Travel, Gift, and Car Expenses (Chapter 3: Gifts) — IRS
- FINRA Raises Gifts Rule Limit to $300, But Lower Limits Still Apply Under Other Rules — Morgan Lewis
- Raising the Limit: FINRA Amends Gift Rule (Rule 3220) — Skadden
Trusted by law firms including Fish & Richardson, Weil, Gotshal & Manges and Bradley.